
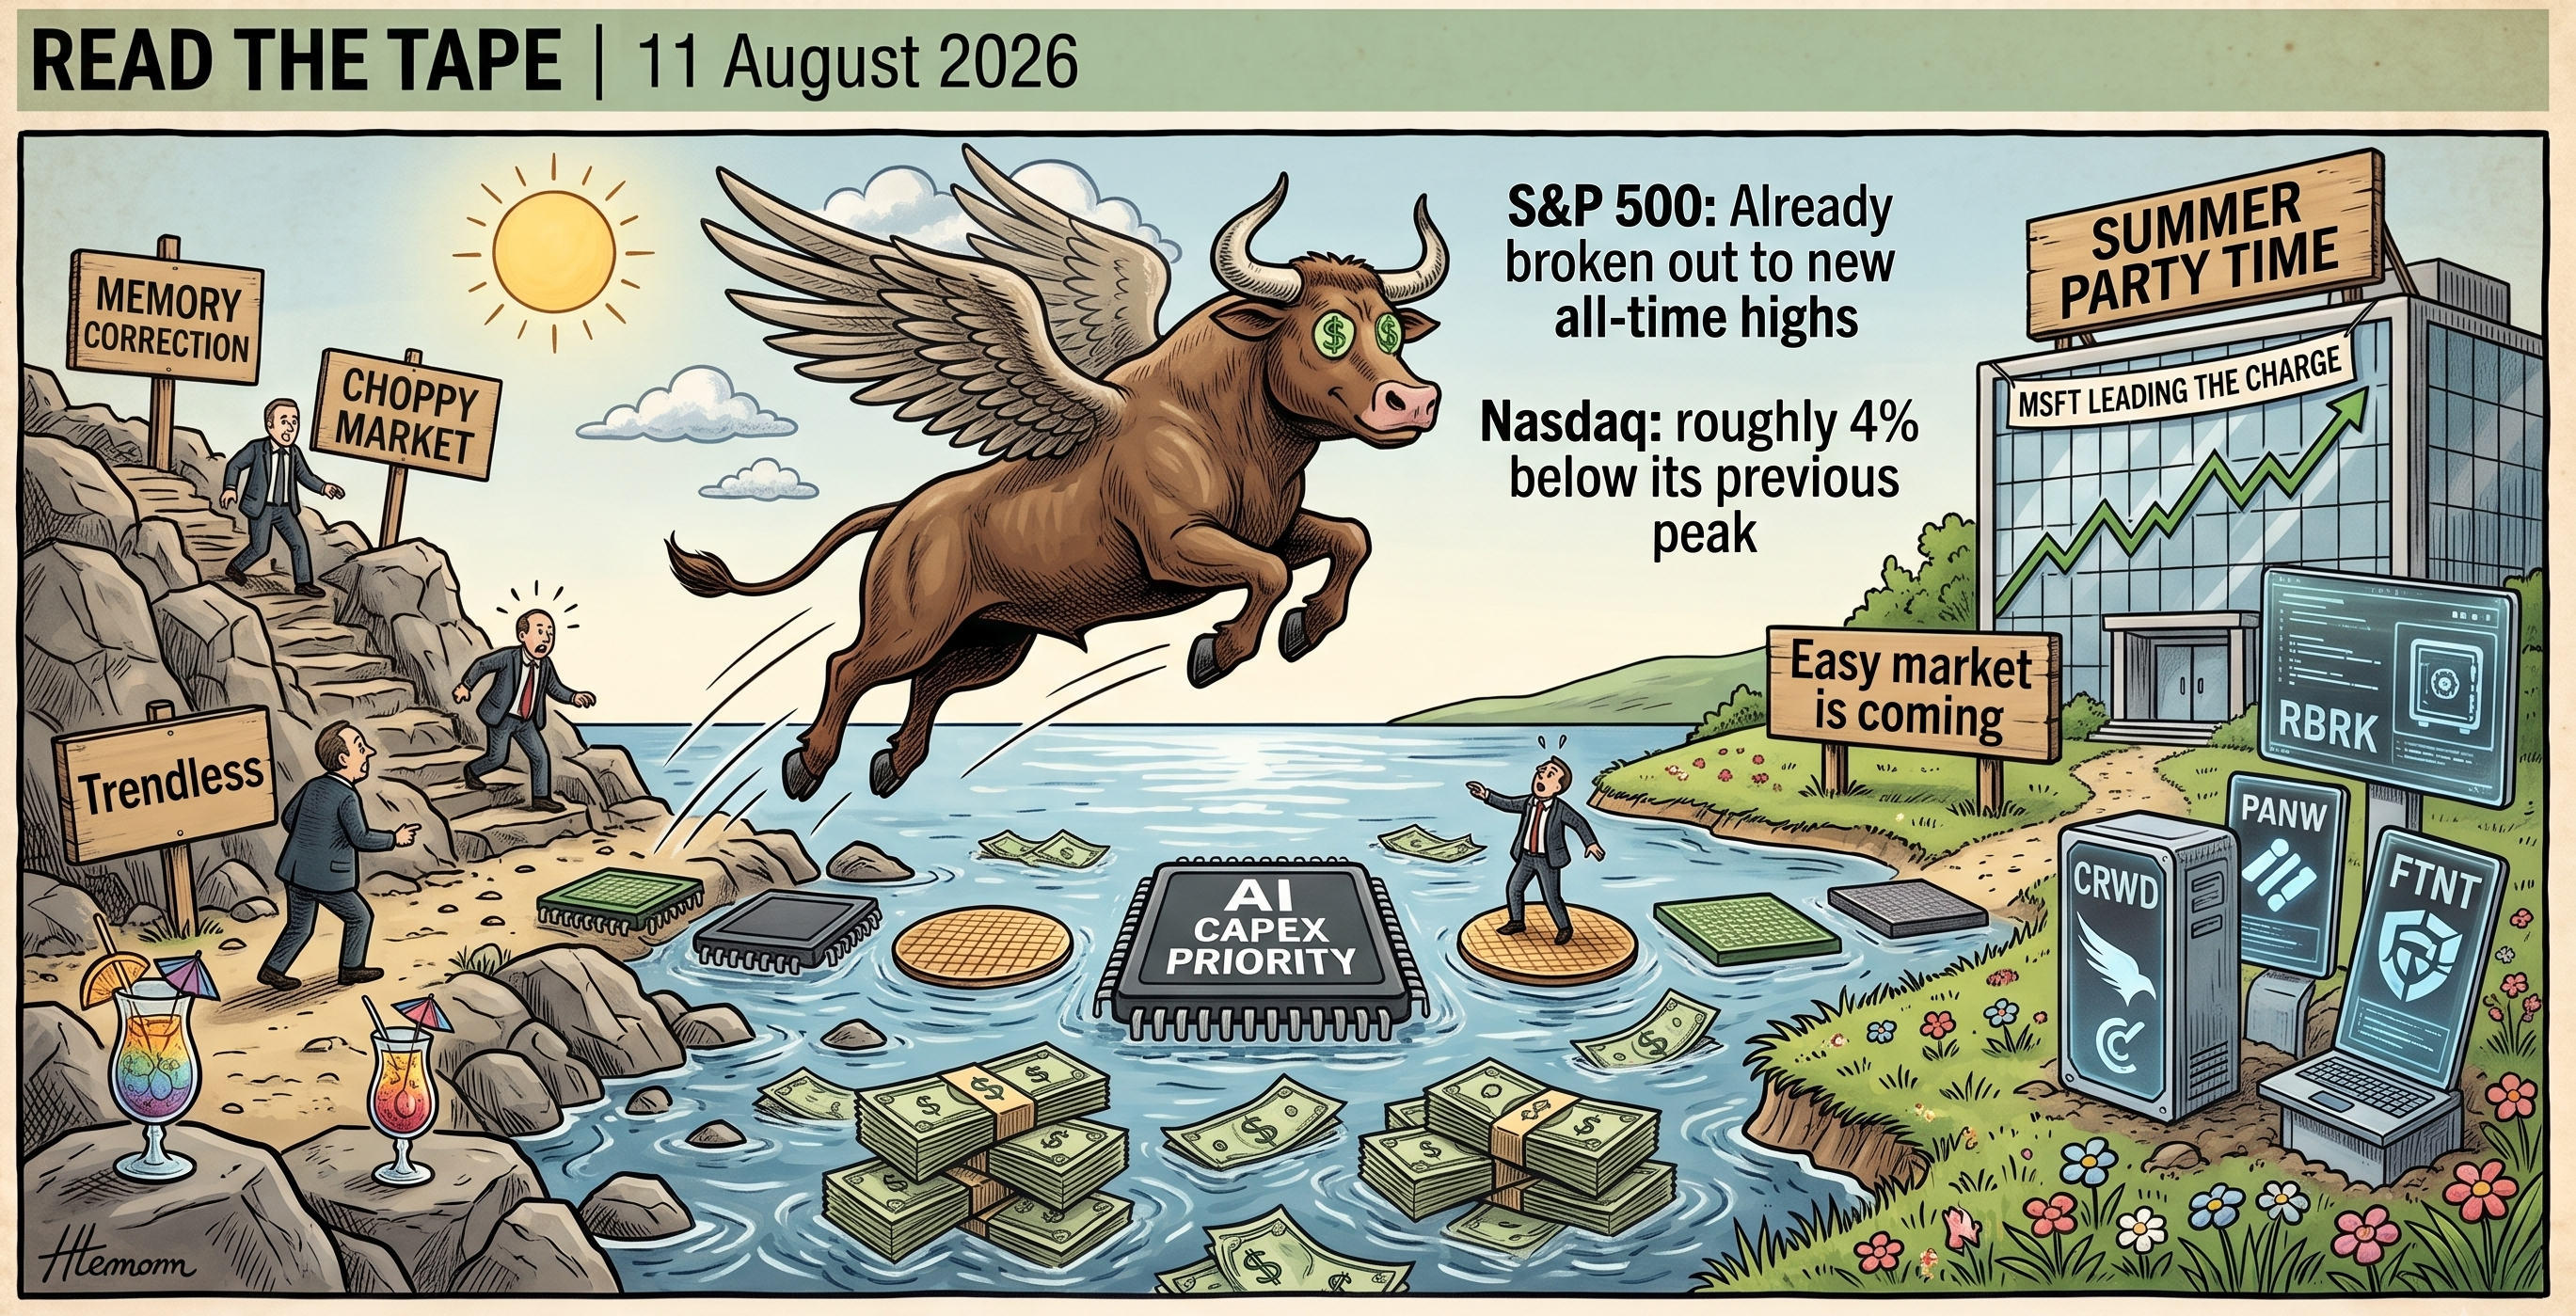
The market experienced a healthy recovery in August, showing signs of a more favorable market environment. While it remains too early to draw definitive conclusions, we are seeing constructive price action and solid base formations across several sectors.
S&P: Already broken out to new all-time highs.

SOX (Semiconductor Index): Has successfully recovered and is holding firm at key support levels.

Nasdaq: Currently sits roughly 4% below its previous peak.

Cybersecurity: The New AI Capex Priority
Cybersecurity names have emerged as an indispensable component of the AI expansion, driven by the need to safeguard corporate data against AI-related threats and the widespread deployment of AI agents.
This group validates a time-tested stock-picking rule: companies that demonstrate relative strength during tough market condition (June/July) tend to be the strongest outperformers when conditions improve. The entire cohort, including CrowdStrike (CRWD), Palo Alto Networks (PANW), Rubrik (RBRK), and Fortinet (FTNT), is breaking out to new highs this month, following their resilient performance in June and July.
While investors worry about overall AI infrastructure overspending, management commentary from leaders like IBM indicates that corporates are prioritizing cybersecurity in their capex budgets.


Big Tech: Sustained Accumulation
Big Tech continues to show solid performance, albeit at a more modest pace than the sharp re-rating seen in late July.
Notably, Microsoft (MSFT) continues to hit new highs following its strong quarterly earnings report on July 30. The initial 15% post-earnings surge—and subsequent upward drift—demonstrates how institutional funds continue to accumulate high-conviction market leaders over time, driving extended re-ratings.


Hardware & AI Infrastructure: Volatility & Supply-Chain Pressure
The hardware side of AI infrastructure remains volatile. Memory and storage leaders from the first half, such as SanDisk (SNDK) and Micron (MU), rebounded from their July “Situational Awareness” lows but remained choppy. Choppiness in these names creates noise, making it harder to confirm if the primary uptrend is still in place.


Meanwhile, the CPU space has pulled back following a solid rebound. Intel’s announcement of a USD15bn stock offering yesterday triggered a sharp sell-off across the sector (Intel -4%, AMD -3%, ARM -5%). This move highlighted broader market concerns regarding the escalating capital expenditures required for chipmakers to maintain their competitive edge.


Selective opportunities in the market
Overall, market conditions have turned considerably more constructive in August. We are seeing a higher prevalence of actionable setups and encouraging price action across multiple sectors. Following two challenging months, this improving backdrop offers selective opportunities for investors to increase market exposure.
The information provided in this note is for educational and informational purposes only and does not constitute financial, investment, or professional advice.

Leave a Reply